
Structured Lender Outreach for Debt Financing
Structured lender outreach for debt financing: lender mapping, controlled distribution, term-sheet comparison and execution for complex debt mandates.

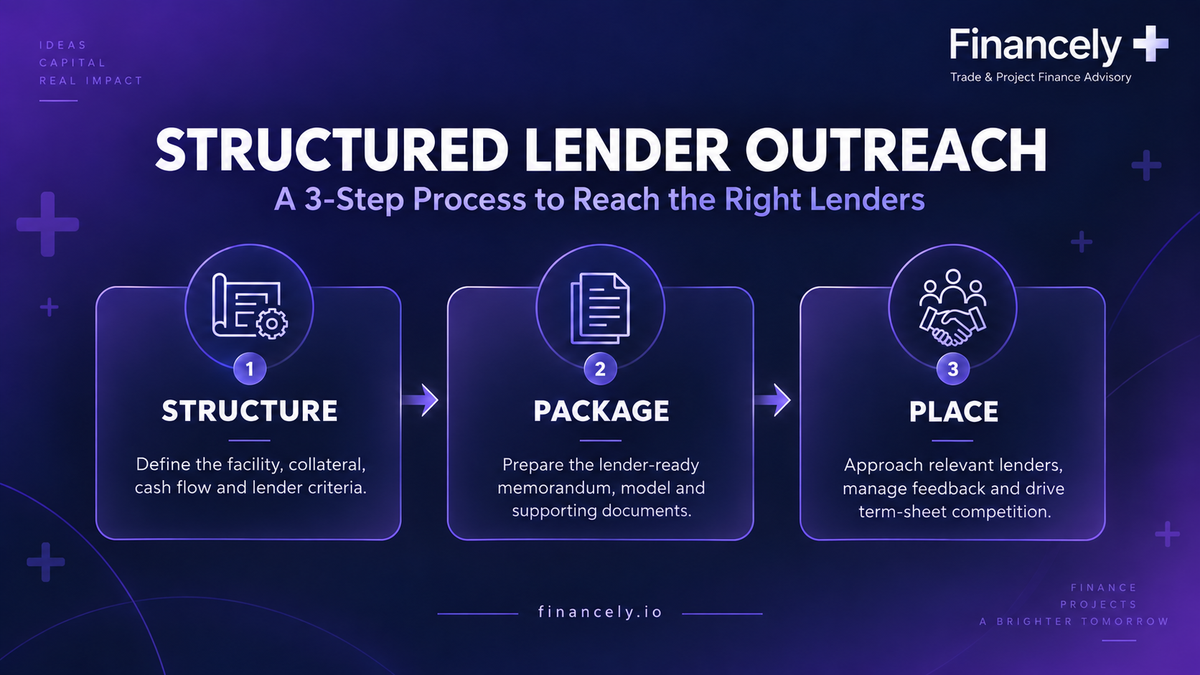
Structured lender outreach is the controlled process of identifying, qualifying and approaching lenders that can underwrite a defined debt financing requirement. It sits between transaction preparation and lender diligence. The work is not a contact-list exercise. The lender universe has to be filtered by product, ticket size, geography, sector, collateral, leverage, repayment source and current credit appetite before any serious distribution begins.
For companies, sponsors, acquirers and asset owners, the objective is to turn a financing requirement into a managed lender process. Financely uses structured lender outreach as part of its broader structured debt advisory work, combining lender mapping, lender-facing materials, sequenced distribution, feedback management and term-sheet analysis.
For adjacent execution guidance, review structured lender outreach service, structured debt advisory definition, and Financely engagement process.
What Structured Lender Outreach Includes
Before outreach, the transaction has to be reduced to a lender-readable credit case. The file should state the borrower, requested facility, use of proceeds, repayment source, proposed security, existing debt, sponsor contribution, transaction timetable and the principal risks a credit team will test.
A disciplined process then maps lenders by mandate rather than brand recognition. Banks, private credit funds, asset-based lenders, specialty finance companies and institutional credit platforms can have materially different underwriting parameters. A lender that is active in one part of the capital structure may be unsuitable for another even when the headline ticket size appears to fit.
- Mapping Screen lenders by product, geography, ticket size, collateral and risk appetite.
- Distribution Release the transaction in controlled batches with consistent lender materials.
- Execution Manage questions, diligence, indicative terms and comparison through selection.
Why Controlled Distribution Matters
Broad, unstructured distribution creates duplicate submissions, inconsistent information and avoidable lender fatigue. A borrower may also lose visibility over who has received the file, which version was sent and what representations were made. Structured lender outreach uses a defined lender list, a distribution log and a controlled information package so the process can be audited.
Sequencing also matters. The first lender group should be close enough to the target structure to produce useful market feedback. If several qualified lenders raise the same issue, the file can be revised before the next group is approached. That is materially different from sending the same request to dozens or hundreds of institutions at once.
What Lenders Expect Before Outreach
Lenders expect evidence, not only a financing narrative. The data room should support the credit proposition with financial statements, management accounts, transaction documents, contracts, collateral information, ownership records and a financial model where appropriate. The exact package changes by transaction type, but the principle is consistent: material assumptions should reconcile to source documents.
The OCC's Comptroller's Handbook reflects the credit administration and risk-management discipline used in regulated bank lending. A borrower does not need to reproduce a bank's internal credit file, but its submission should be organized so an underwriter can test leverage, repayment, collateral and downside risk efficiently.
From Outreach to Term Sheets
Serious lender outreach is measured by decision progress, not by the number of emails sent. Responses need to be classified into information requests, structural objections, written declines, indicative terms and executable proposals. A term sheet should then be compared across economics and structure, including pricing, fees, tenor, amortization, covenants, security, conditions precedent, reporting and any mandatory prepayment provisions.
For routine lender-ready transactions, Financely generally targets an indicative 45-day execution window for structured outreach and initial term-sheet development. That is not a financing guarantee. Timing remains dependent on file quality, lender diligence, client responsiveness, credit approval and transaction complexity.
When Financely Is a Fit
Financely works on paid B2B mandates where the client is prepared to retain professional advisers and provide the documentation required for lender review. We do not act as a direct lender and do not guarantee lender approval, pricing or closing.
Clients that want execution can start through the Structured Debt Advisory Engagement process. The initial review determines whether the mandate is ready for lender mapping and distribution or requires additional structuring first.
FAQ About Structured Lender Outreach for Debt Financing
Is structured lender outreach the same as a lender introduction?
No. An introduction is one event. Structured lender outreach includes lender selection, preparation, sequenced distribution, information control, follow-up, lender feedback, term-sheet comparison and execution support.
How many lenders should be approached?
There is no fixed number. The relevant universe depends on transaction type, size, geography, security and lender appetite. A smaller qualified list is generally more useful than a large undifferentiated database.
Does Financely work on success-fee-only mandates?
No. The work required before lender commitment includes underwriting preparation, mapping, lender materials and distribution. Financely uses paid mandates, with any success fee addressed separately in the engagement terms.
Run a Structured Lender Outreach Mandate
For a live debt requirement, Financely can structure the lender case, map the relevant credit universe and coordinate controlled distribution through term-sheet review and execution.
Start Structured Lender Outreach